
Rachel Reeves’ ISA savings reform has taken an unexpected turn. The controversial proposal to reduce the annual Cash ISA allowance from £20,000 to £12,000 for savers under 65 has been abandoned following the UK Autumn Budget on 28 October 2026.
New Chancellor John Healey confirmed that the Cash ISA allowance will remain at £20,000 for adults of all ages, reversing one of the previous Chancellor’s most significant personal savings proposals.
The decision protects the ability of millions of savers to build tax-free cash reserves without being pushed towards stock-market investments. However, it does not mean that all savings-related tax changes have disappeared.
From 6 April 2027, the Government plans to increase taxes on savings income outside ISAs to 24%, 44% and 49%, depending on the individual’s tax band. Meanwhile, new incentives for first-time investors and major changes to Lifetime ISAs are also being developed.
Our analysis of the revised framework shows that the biggest financial advantage is not simply the preservation of the £20,000 annual allowance.
It is the combination of continued tax-free saving, greater flexibility between savings and investments, and the opportunity to manage exposure to higher future savings taxes.
For entrepreneurs, company directors, self-employed professionals and households building substantial cash reserves, these distinctions are particularly important.
What Is the Latest Update on Rachel Reeves’ ISA Savings Reform?
The latest development is the Government’s decision to reverse the planned Cash ISA reduction before its scheduled implementation on 6 April 2027.
Rachel Reeves originally announced the policy at the Autumn Budget on 26 November 2025. Under the proposal, individuals younger than 65 would have been restricted to £12,000 in annual Cash ISA contributions, while retaining an overall £20,000 ISA allowance.
The intention was to encourage savers to invest more money in stocks and shares, with the wider objective of strengthening long-term wealth creation and supporting UK capital markets.
The proposal represented a 40% reduction in the amount younger savers could contribute to Cash ISAs each year.
Although the policy advanced through consultation and regulations during 2026, the subsequent Budget reversed the Government’s position.
Chancellor John Healey stated in his 28 October Budget speech:
“I will not go ahead with the cut to the tax-free amount that people can put into a cash ISA.”
The Government has instead chosen to retain the existing allowance and explore additional incentives for people entering the investment market for the first time.
Key ISA Rules Following the October 2026 Budget
| ISA measure | Earlier reform plan | Latest position |
| Overall adult ISA allowance | £20,000 | £20,000 retained |
| Cash ISA limit for under-65s | Reduced to £12,000 | £20,000 retained |
| Cash ISA limit for over-65s | £20,000 | £20,000 retained |
| Reduction in cash contribution capacity | 40% | Cancelled |
| Stocks and Shares ISA allowance | Within £20,000 overall allowance | Unchanged |
| 22% charge on cash interest in investment ISAs | Planned | Abandoned with reforms |
| Transfers from investment ISAs into Cash ISAs | Restrictions planned | Restrictions abandoned |
| New first-time investment incentive | Not part of the original framework | Under development |
| Relevant date | 6 April 2027 | Existing Cash ISA limit continues |
The important distinction is that the allowance reduction has been cancelled, not merely postponed by a few months.
The Treasury has indicated that secondary legislation will be introduced in November 2026 to implement the revised Cash ISA position, replacing the policy direction previously reflected in the September regulations.
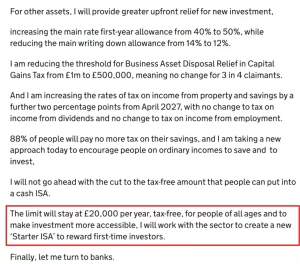
Chancellor John Healey confirmed in the 28 October 2026 Budget speech that the annual Cash ISA allowance will remain at £20,000 for people of all ages.
Why Did the Government Reverse Rachel Reeves’ Cash ISA Reform?
The reversal reflects a disagreement about the best way to encourage British households to move from saving into investing.
The original proposal assumed that restricting Cash ISA contributions would encourage people to use more of their tax-free allowance for equities, investment funds and other eligible investments.
However, the financial consequences were not straightforward.
Cash ISAs typically serve a different purpose from Stocks and Shares ISAs. Many savers use cash accounts for emergency funds, property deposits, retirement reserves and money they cannot afford to expose to short-term financial market volatility.
Reducing access to tax-free cash saving would not necessarily turn those individuals into investors.
Some might simply transfer additional savings into ordinary taxable accounts, while others could take on investment risk that was inappropriate for their financial circumstances.
The proposed reform also attracted concerns about compliance costs, the complexity of different age-based limits and restrictions on transferring assets between account types.
Tom Selby, Director of Public Policy at AJ Bell, criticised the original approach as “painfully convoluted”, despite recognising that encouraging long-term investment was a legitimate policy objective.
The decision to reverse the policy therefore represents more than a technical amendment. It marks a change in how the Government intends to influence household financial behaviour.
Rather than reducing the attractiveness of cash savings, the Government is now investigating ways to make investing more appealing.
Why Cash Savings Still Matter to the Wider Economy?
Cash ISA deposits have significance beyond individual household finances.
Banks and building societies use deposits as part of their broader funding arrangements, helping support lending, including mortgages.
A reduction in Cash ISA contributions could have affected how some institutions attract deposits, although the extent would depend on where savers moved their money.
There is also a behavioural consideration. Financial security often comes before investment risk.
A household with a reliable emergency fund may be more comfortable making long-term investment decisions than one forced to choose between tax efficiency and access to cash.
Matt Benchener, Chief Executive of Hargreaves Lansdown, welcomed the Budget reversal, stating:
“The Government’s decision to leave Cash ISAs as they are, is the right one.”
He also highlighted the importance of Cash ISAs as an entry point into saving and investing.
Our assessment is that a successful investment strategy should distinguish between money needed for financial resilience and capital available for long-term growth.
How Have the ISA Rules Changed Between 2025, 2026 and 2027?
The timeline matters because older financial articles and government documents may still describe the £12,000 limit as an upcoming change.
| Date | Development | Significance |
| 26 November 2025 | Rachel Reeves announced the proposed Cash ISA reduction | Established the £12,000 proposal |
| 23 June 2026 | Government announced anti-circumvention measures | Added restrictions on transfers and cash-like investments |
| July 2026 | HMRC conducted technical consultation | Providers examined implementation requirements |
| September 2026 | ISA amendment regulations were made and laid before Parliament | Prepared for April 2027 implementation |
| 28 October 2026 | Autumn Budget reversed the proposed reduction | Restored the policy commitment to the full £20,000 Cash ISA allowance |
| 29 October 2026 | New Lifetime ISA withdrawal rules take effect | Reduces a particular property-related withdrawal charge |
| November 2026 | Further Cash ISA secondary legislation expected | Intended to implement the Budget reversal |
| 6 April 2027 | Higher savings income tax rates scheduled | Increases the importance of tax-efficient savings |
The September 2026 policy documents remain useful historical records of the original reform. They should not, however, be treated as the Government’s latest policy position following the October Budget.
This distinction is important for anyone reviewing financial plans previously based on the assumption that Cash ISA contributions would be restricted from April 2027.
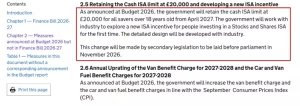
HMRC’s Budget 2026 tax legislation overview confirms that the £20,000 Cash ISA limit will be retained and that updated secondary legislation is expected in November 2026.
What Happens to the Proposed 22% Tax on Cash Held in Stocks and Shares ISAs?
One of the less widely understood elements of Rachel Reeves’ original reform was the planned charge on interest earned by cash held within investment ISAs.
Under the earlier framework, investors would have faced a flat-rate 22% charge on qualifying cash interest or alternative-finance returns inside Stocks and Shares ISAs and Innovative Finance ISAs.
This measure was designed to prevent savers from bypassing the £12,000 Cash ISA limit by putting their money into an investment ISA and leaving it in cash.
For example, a £10,000 uninvested cash balance earning 4% annually would generate £400 of interest. Under the abandoned proposal, a 22% charge would have amounted to £88.
The Government also intended to prevent qualifying investment ISA portfolios from consisting entirely of money market funds, while restricting certain transfers from investment ISAs into Cash ISAs.
These anti-circumvention measures have been abandoned alongside the underlying allowance reduction.
As a result, the planned 22% interest charge will not be introduced under the cancelled framework, and existing ISA transfer flexibility is being preserved.
This is especially relevant to investors who temporarily hold cash while deciding where to allocate their portfolios.
It is also beneficial to individuals who may need to move away from market investments into more predictable cash holdings as their financial circumstances change.
Will the Cash ISA Allowance Remain £20,000 in 2027?
Yes. Under the latest Budget announcement, the Government is retaining the £20,000 annual Cash ISA allowance for eligible adults from April 2027.
The overall adult ISA allowance also remains £20,000.
This means someone can put the full allowance into Cash ISAs or spread it across other eligible ISA types according to their objectives and the applicable product rules.
ISA Contribution Examples
| Savings approach | Cash ISA | Other adult ISAs | Total contribution |
| Cash-focused saver | £20,000 | £0 | £20,000 |
| Balanced cash and investments | £10,000 | £10,000 | £20,000 |
| Investment-focused saver | £2,000 | £18,000 | £20,000 |
| First-home saver using a Lifetime ISA | £12,000 | £4,000 LISA + £4,000 Stocks and Shares ISA | £20,000 |
| Smaller saver | £5,000 | £0 | £5,000 |
The Lifetime ISA has its own maximum annual contribution of £4,000, which counts towards the standard adult £20,000 allowance.
Junior ISAs operate separately, with a £9,000 contribution limit for the 2026/27 and 2027/28 tax years.
An important point is that the ISA allowance applies to contributions made during a tax year, not the total amount someone is permitted to hold in ISAs.
For example, a person who already has £85,000 accumulated in Cash ISAs can continue holding that balance and potentially subscribe another £20,000 in the following tax year, subject to their eligibility and the prevailing rules.
There is no requirement to withdraw existing ISA funds simply because they exceed one year’s allowance.
For a more detailed breakdown of annual contribution rules, the tax-free Cash ISA allowance remains an important part of individual savings planning.
How Will Higher Savings Tax Rates Affect ISA Holders in April 2027?
Although the Cash ISA allowance reduction has been cancelled, higher tax rates on savings income outside ISAs remain an important part of the Budget.
The Autumn Budget 2025 originally announced a two-percentage-point increase in savings income tax rates for April 2027.
The Autumn Budget 2026 announced a further two-percentage-point increase.
Taken together, the planned changes produce a four-percentage-point increase from the rates applying in 2026/27.
Savings Income Tax Rates: 2026/27 Compared With 2027/28
| Taxpayer category | 2026/27 savings tax rate | Planned rate from April 2027 | Increase |
| Basic rate | 20% | 24% | +4 percentage points |
| Higher rate | 40% | 44% | +4 percentage points |
| Additional rate | 45% | 49% | +4 percentage points |
These rates apply to taxable savings income, not interest earned within a qualifying Cash ISA.
They also do not mean that every saver will pay tax on their interest. The Personal Savings Allowance and, where applicable, the starting rate for savings remain relevant.
How Much Savings Interest Can You Earn Before Paying Tax?
| Taxpayer | Personal Savings Allowance |
| Basic-rate taxpayer | £1,000 |
| Higher-rate taxpayer | £500 |
| Additional-rate taxpayer | £0 |
Eligible lower-income savers may also qualify for the separate starting rate for savings.
The distinction between ordinary taxable interest and protected ISA interest therefore becomes increasingly important as savings balances grow.
Those concerned about changes to how banks provide interest information to HMRC should also understand the wider HMRC rules affecting savings accounts, particularly where personal savings generate taxable income.
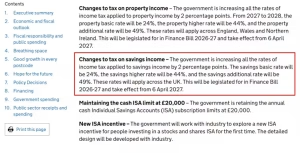
The Autumn Budget 2026 confirms planned savings income tax rates of 24%, 44% and 49% from 6 April 2027, while keeping qualifying ISA interest tax-free.
How Much Tax Could a Cash ISA Save Under the New Rules?
The financial benefit depends on the amount saved, the interest rate, other savings income and the individual’s tax position.
Consider a hypothetical saver with £20,000 earning 4% annually.
The interest earned over one year would be approximately £800, assuming the balance and rate remain constant.
Inside a Cash ISA, that £800 would generally remain free from UK Income Tax.
Outside an ISA, the result depends on the individual’s remaining tax-free savings allowances.
Example: £20,000 Earning 4% Interest
| Taxpayer situation | Annual interest | Potential tax from April 2027 | Interest after tax |
| Basic-rate taxpayer with full £1,000 PSA available | £800 | £0 | £800 |
| Higher-rate taxpayer with full £500 PSA available | £800 | £132 | £668 |
| Additional-rate taxpayer | £800 | £392 | £408 |
| Interest held inside a Cash ISA | £800 | £0 | £800 |
These are illustrative calculations. They assume the stated tax bands, 4% annual interest and no additional exemptions beyond those specified.
For the higher-rate taxpayer, £300 exceeds the available £500 Personal Savings Allowance, producing £132 of tax at 44%.
For the additional-rate taxpayer, the full £800 is taxable outside an ISA at the proposed 49% savings income tax rate.
The comparison demonstrates why an ISA can become valuable even when two accounts offer identical gross interest rates.
A Larger Savings Example
Imagine a higher-rate taxpayer holding £50,000 in ordinary savings accounts at a hypothetical 4% annual interest rate.
Annual interest would be £2,000.
After the £500 Personal Savings Allowance, £1,500 would remain taxable.
At the proposed 44% savings income tax rate, the resulting tax would be £660, leaving £1,340 after tax.
If the individual instead held £20,000 in a Cash ISA and £30,000 in ordinary savings, and both paid 4%, the calculation would change:
| Savings location | Balance | Annual interest | Tax treatment |
| Cash ISA | £20,000 | £800 | Tax-free |
| Ordinary savings | £30,000 | £1,200 | £500 PSA applies |
| Taxable ordinary interest | — | £700 | 44% rate |
| Tax due | — | — | £308 |
| Combined interest after tax | — | — | £1,692 |
The ISA arrangement would produce £352 more after-tax interest annually in this hypothetical example.
Actual savings will depend on product rates, available allowances, the individual’s wider tax position and any existing ISA balances.
The example illustrates tax efficiency rather than promising a particular investment return.
What Are the Advantages and Disadvantages of the ISA Reform Reversal?
The October Budget reversal offers clear advantages to cash savers, but there are broader economic trade-offs.
Our Editorial Assessment
The following percentages are qualitative editorial scores used to assess the policy’s practical strengths. They are not consumer survey results, independently measured satisfaction ratings or forecasts of investment returns.
| Assessment area | Editorial score | Our interpretation |
| Cash savings flexibility | 95% | Preserving the full £20,000 limit supports different short-term savings goals |
| Simplicity of ISA rules | 90% | Removing age-based limits and anti-circumvention restrictions reduces complexity |
| Protection from taxable savings interest | 90% | The Cash ISA remains particularly useful for savers above their tax-free allowances |
| Support for long-term investment participation | 65% | The underlying investment objective remains, but further incentives are not yet fully designed |
| Clarity of the proposed Starter ISA | 35% | The Government has not announced enough detail to assess the final incentive |
The strongest feature of the reversal is flexibility.
A saver can maintain accessible reserves without being forced into a particular investment product to obtain tax-free treatment.
However, a £20,000 Cash ISA allowance does not guarantee superior returns.
Cash savings can lose purchasing power when inflation exceeds interest earned. Long-term investors may therefore still benefit from diversified investment portfolios, provided they can accept market volatility.
The decision between preserving capital and pursuing higher long-term returns should depend on financial objectives rather than tax policy alone.
What Do Financial Experts Think About the ISA Reform Reversal?
The financial sector has expressed differing views about the original proposal and the subsequent reversal.
Those welcoming the decision generally argue that savers should have the freedom to decide whether their money belongs in cash or investments.
Chris Hayward, Policy Chairman of the City of London Corporation, welcomed the emphasis on simplicity and said:
“The focus now should be on giving people the information, guidance and confidence they need to make informed investment decisions.”
This reflects the argument that participation in financial markets depends on knowledge and trust, not simply on changing contribution limits.
However, not all investment professionals support the reversal.
Michael Healy, Chief Executive of IG Consumer, criticised the decision because he believes it misses an opportunity to encourage long-term household wealth creation and investment in British businesses.
His position raises an important economic concern: Britain needs both stable household savings and greater participation in productive investment.
The central disagreement is therefore about policy design, rather than whether investing can create long-term wealth.
From our financial analysis, the most sustainable approach is likely to combine basic financial education, accessible investment products, suitable risk disclosure and consistent savings incentives.
The challenge is persuading people to invest when it is appropriate for them, without undermining the role of cash in household financial stability.
What Is the New Starter ISA Announced in the 2026 Budget?
The Chancellor has announced plans to work with the financial services industry on a new incentive intended to encourage first-time Stocks and Shares ISA investors.
The initiative was described in the Budget speech as a new Starter ISA.
However, the Government has not yet finalised the detailed design.
It is therefore too early to say whether the incentive will involve a government bonus, matching contributions, fee reductions or another mechanism.
No confirmed contribution allowance, launch date or eligibility criteria have been published for the proposed investment incentive.
A potential advantage would be encouraging individuals with sufficient cash reserves to begin investing gradually.
An effective introductory product could help first-time investors understand diversification, long-term compounding and investment costs before allocating substantial sums.
However, creating another ISA product also raises questions about complexity. A new incentive will need to offer a clearly understandable benefit rather than simply adding another layer of financial administration.
People already considering investments should assess their financial goals rather than make decisions solely on the expectation of an incentive that has not yet been specified.
For those comparing asset classes, understanding where to invest money for long-term returns can help distinguish cash reserves from capital intended for long-term investment.
How Will Lifetime ISAs Change Following the October 2026 Budget?
The Budget contains significant developments for first-time homebuyers.
The Government has announced a new First Time Buyer ISA, expected to launch in April 2029 and replace the Lifetime ISA for new savers.
This is separate from the proposed Starter ISA incentive for first-time Stocks and Shares ISA investors.
The First Time Buyer ISA is intended to preserve the benefit of a 25% government bonus on eligible savings.
The announced framework includes contributions of up to £4,000 annually, a maximum government bonus of £20,000, and support for first-home purchases worth up to £450,000.
The new product is intended to have no upper age restriction, while the bonus would be paid when funds are withdrawn for a qualifying first-home purchase.
Existing Lifetime ISA holders will be able to continue contributing to and using their accounts under the existing framework.
What Happens to the Lifetime ISA Withdrawal Penalty?
The Government has also announced an immediate change from 29 October 2026 for qualifying first-time buyers purchasing homes above the £450,000 Lifetime ISA property cap.
For these specific purchases, the withdrawal charge falls from 25% to 20%.
Other unauthorised withdrawals remain subject to the 25% charge.
For example, assuming no investment growth or charges:
| Withdrawal situation | Account value | Withdrawal charge | Amount received |
| Previous 25% charge | £5,000 | £1,250 | £3,750 |
| New qualifying 20% charge | £5,000 | £1,000 | £4,000 |
| Difference | — | £250 less | £250 more |
The example assumes £4,000 in personal contributions and a £1,000 government bonus.
The lower 20% charge effectively removes the bonus without reducing the original £4,000 contribution in this simplified example.
This is a meaningful development for first-time buyers who find suitable properties above the existing cap.
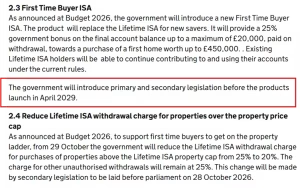
HMRC’s October 2026 Budget guidance sets out the new First Time Buyer ISA planned for April 2029 and the reduced 20% Lifetime ISA withdrawal charge for qualifying higher-value property purchases.
How Does the ISA Decision Affect Entrepreneurs and Small Business Owners?
For entrepreneurs, the value of the Cash ISA allowance extends beyond ordinary personal saving.
Many business owners experience uneven income from salary, dividends, self-employment or profits extracted from their companies.
That variability increases the importance of maintaining accessible personal cash reserves.
A business owner who receives a substantial dividend in one year may wish to preserve part of the proceeds for future household expenditure, rather than commit all available capital to long-term investments.
The preservation of the full Cash ISA allowance provides greater flexibility for that planning.
However, there is an important distinction between business cash and personal savings.
A limited company cannot simply place its working capital into a director’s personal ISA while continuing to treat the money as company-owned funds.
The funds must first become the individual’s money through an appropriate route, such as salary, a lawful dividend or repayment of a genuine director’s loan balance.
Any associated tax consequences should be considered before the money is contributed to an ISA.
A Practical Example for a Company Director
Suppose a company director has £30,000 in personal savings after meeting their tax obligations.
They may decide to allocate £20,000 to a Cash ISA and retain £10,000 in a separate accessible savings account, depending on their wider finances.
Under the abandoned reform, an under-65 director would have been restricted to £12,000 of annual Cash ISA contributions from April 2027.
Under the revised policy, the full £20,000 contribution capacity remains available.
This could be particularly useful for business owners whose personal cash flows change significantly between tax years.
Nevertheless, contributions should not compromise money required for Corporation Tax, VAT, payroll or other company liabilities.
For founders reviewing wider fiscal policy, Rachel Reeves’ earlier Budget tax changes provide context for why savings decisions should be assessed alongside dividends, capital gains and company tax planning.
Will the ISA Reform Reversal Benefit Pensioners?
Pensioners may benefit from the continuation of the full Cash ISA allowance because predictable returns and capital accessibility often become important during retirement.
Under Rachel Reeves’ original proposal, individuals aged 65 and above would already have retained the £20,000 Cash ISA allowance.
The primary direct change therefore affects those younger than 65.
However, the reversal also simplifies the overall system, removing the need for separate age-based cash contribution limits.
Someone approaching retirement can continue using the full allowance before reaching 65.
This may be especially relevant to individuals receiving redundancy payments, pension lump sums or other legitimate personal funds.
Savings interest outside ISAs can also increase taxable income, even where pension income remains relatively stable.
For this reason, retirees should assess the interaction between pensions and savings interest rather than compare accounts only by headline rates.
Understanding how savings interest affects pensioner Income Tax can be particularly useful when retirement income comes from several sources.
Should You Keep Money in a Cash ISA or Invest in Stocks and Shares?
The Government’s decision restores greater freedom of choice, but it does not eliminate the need to balance investment risk and liquidity.
Cash ISAs may be better suited to money required within the next few years, emergency savings and individuals who prioritise capital preservation.
Stocks and Shares ISAs may be appropriate for longer investment periods where the individual can tolerate fluctuations and potential losses.
A Cash ISA normally provides a stated interest rate, although rates can change unless fixed by contract.
Investments do not promise the same stability. Their values can fall as well as rise, and investors may receive less than they originally contributed.
For example, an investor could achieve stronger growth over a long period through diversified equities, but a market decline shortly before a planned property purchase could materially reduce available funds.
The relevant question is not whether one ISA is universally better.
It is whether the financial product matches the purpose of the money.
For a business owner, that could mean keeping personal emergency reserves in cash while using separate investment funds for long-term wealth building.
For a young professional, it might involve maintaining accessible savings while investing a manageable monthly amount.
The ISA wrapper offers favourable tax treatment, but it does not remove the underlying differences between saving and investing.
What Should UK Savers Do Before the End of the 2026/27 Tax Year?
The tax year ends on 5 April 2027. Although the planned Cash ISA allowance reduction has been cancelled, reviewing available allowances still makes financial sense.
Our recommended review focuses on the following actions:
- Check existing ISA contributions. Confirm how much of the £20,000 allowance has already been used across eligible adult ISA accounts.
- Review accessible cash reserves. Ensure emergency money and near-term expenditure are not exposed to unnecessary investment risk.
- Compare after-tax savings returns. A Cash ISA is not automatically the best-paying account; compare interest rates and tax treatment together.
- Review the Personal Savings Allowance. Higher-rate and additional-rate taxpayers may benefit more immediately from ISA protection when ordinary interest is taxable.
- Use formal ISA transfers. Avoid withdrawing money simply to move it between providers where a formal transfer would preserve the tax wrapper.
- Consider the April 2027 savings tax changes. Higher rates may increase the long-term value of tax-free interest.
- Separate personal and business cash. Directors and founders should ensure that any ISA contributions are made using funds they legally own.
Unused annual ISA allowance generally cannot be carried into the next tax year.
Savers should nevertheless avoid making rushed decisions purely to use the allowance. Paying down expensive debt or maintaining necessary liquidity may provide greater financial value.
What Is Our Overall Assessment of Rachel Reeves’ ISA Savings Reform?
The October 2026 decision represents a substantial reversal of Rachel Reeves’ original ISA strategy.
The proposed £12,000 Cash ISA limit would have reduced the annual cash contribution capacity of under-65 savers by 40%, while introducing additional restrictions intended to encourage investment.
The latest approach preserves the full £20,000 allowance and abandons the planned anti-circumvention measures, while developing new incentives for first-time investors.
Our evaluation is that the revised policy offers greater flexibility to individual savers and avoids some of the administrative complications associated with the original proposal.
However, the broader challenge remains unresolved.
Britain needs households to build financial resilience, but it also needs more people with suitable investment horizons to participate confidently in long-term investing.
A policy that supports both outcomes is more balanced than one that treats cash savings and investments as direct substitutes.
For entrepreneurs and financially active households, the most important practical consequence is the ability to continue using Cash ISAs for personal reserves while making separate investment decisions based on genuine risk tolerance and longer-term objectives.
Conclusion
Rachel Reeves’ ISA savings reform has ultimately resulted in a different policy outcome from the one originally proposed.
The 40% reduction in Cash ISA contribution capacity for younger savers has been abandoned, and the £20,000 annual allowance will continue under the revised Government plan.
That decision provides greater certainty for people using Cash ISAs to protect emergency funds, property deposits, retirement savings and other personal reserves.
At the same time, the planned April 2027 increases in savings income tax make it increasingly important to understand the difference between tax-free ISA interest and taxable interest earned elsewhere.
The proposed Starter ISA and the new First Time Buyer ISA could also shape how younger households save and invest in the coming years.
Our conclusion is that the central financial lesson remains unchanged: tax efficiency matters, but a good savings strategy must also account for accessibility, financial risk, inflation and the purpose of the money.
The continuation of the full Cash ISA allowance gives UK savers more freedom to make those decisions on their own terms.
Frequently Asked Questions About Rachel Reeves’ ISA Savings Reform
Has Rachel Reeves’ £12,000 Cash ISA Limit Been Scrapped?
Yes. The Government announced on 28 October 2026 that the planned reduction would not proceed. The £20,000 annual Cash ISA allowance is being retained.
How Much Can I Put Into a Cash ISA in 2027?
Under the latest announced policy, eligible adults can contribute up to £20,000 annually to Cash ISAs, subject to the overall ISA contribution limit.
Will the Cash ISA Allowance Be Different for People Under 65?
No. The Government has abandoned the proposed age-based distinction, retaining the £20,000 Cash ISA limit for adults of all ages.
Will the 22% Tax on Cash in Stocks and Shares ISAs Still Apply?
No. The proposed flat-rate charge was part of the abandoned ISA reform package and will not proceed as originally planned.
Are Existing Cash ISA Savings Still Tax-Free?
Yes. Qualifying interest earned inside a Cash ISA remains tax-free, and existing balances do not use up another year’s allowance simply by remaining invested.
Will Savings Interest Outside ISAs Be Taxed More Heavily?
The Government plans to increase savings income tax rates to 24%, 44% and 49% from 6 April 2027. Allowances and individual tax circumstances still determine whether tax is payable.
Is the New Starter ISA Available Now?
No. The Government is exploring a new incentive for first-time Stocks and Shares ISA investors, but its detailed terms and launch date have not been confirmed.
What Is Happening to the Lifetime ISA?
A new First Time Buyer ISA is planned for April 2029. Meanwhile, qualifying Lifetime ISA withdrawals for first-home purchases above the £450,000 property cap benefit from a reduced 20% charge from 29 October 2026.
Can a Limited Company Open a Cash ISA?
No. Cash ISAs are personal accounts for eligible individuals. Company funds must be dealt with separately and cannot simply be deposited as company money into a director’s personal ISA.
Should I Move All My Savings Into a Cash ISA?
Not necessarily. The appropriate decision depends on interest rates, tax allowances, liquidity requirements, debt, investment objectives and personal circumstances.